
Does Your Daycare Have Liability Insurance Why It Matters for Parents
Choosing a daycare often comes down to trust. The teachers seem kind, the rooms feel clean, the schedule works, and the children look happy. But there is one practical question that deserves a place next to curriculum, meals, and nap routines: Does the daycare carry liability insurance?
It may not be the first question that comes to mind during a tour, but it is one of the clearest signs that a childcare provider takes safety and responsibility seriously. Liability insurance does not prevent every accident. Children trip, fall, bump heads, spill paint, and test limits. What it does provide is a financial safety net when something goes wrong and a family, child, staff member, or visitor is affected.
This article is for general information only. Insurance rules, licensing requirements, and coverage details vary by state and provider, so parents should verify details directly with the daycare, the insurer, and local licensing agencies when needed.

What liability insurance means for a daycare
Liability insurance helps protect a daycare if someone claims the center caused injury, harm, or property damage. In simple terms, it can help pay for legal costs, settlements, medical expenses, or other covered losses when a claim falls within the policy.
For a daycare, this matters because childcare involves constant responsibility. Staff members supervise active children, serve snacks, manage playground time, help with toileting, clean toys, and communicate with families. Even careful centers can face incidents.
A daycare’s insurance may include different types of coverage, such as:
General liability coverage This may apply when someone is injured on the property or when property damage occurs.
Professional liability coverage This may apply to claims related to supervision, judgment, or care decisions.
Abuse and molestation coverage Some policies include or offer separate coverage for claims involving abuse. Parents should ask directly because this coverage is not automatic in every policy.
Commercial auto coverage This matters if the daycare transports children in a van or other vehicle.
Workers’ compensation insurance This protects employees who are injured at work. It is usually separate from liability coverage, but it can reflect whether the business is operating responsibly.
Not every daycare has the same policy. A small home daycare may carry a different type or amount of coverage than a larger childcare center. Some centers may meet state minimums, while others may buy broader coverage.
The key is not to become an insurance expert. The goal is to confirm that the daycare has active coverage that fits the way it operates.
Why liability insurance matters in everyday childcare
Parents do not enroll children expecting worst-case events. Most days are ordinary. A child finger-paints, eats lunch, listens to a story, naps, plays outside, and comes home with a crumpled art project.
Still, ordinary childcare includes real risks.
A toddler may fall from playground equipment. A preschooler may have an allergic reaction after eating the wrong snack. A visitor may slip on a wet entryway floor. A child may be injured during a field trip. A staff member may make a supervision mistake that leads to harm.
Good daycares reduce these risks through training, safe equipment, clear procedures, and strong communication. Insurance adds another layer of protection. It helps make sure a covered claim does not turn into chaos for everyone involved.
For parents, coverage matters because it can affect:
How quickly expenses are addressed after an incident
Whether the daycare can afford legal representation
Whether the center can stay open after a serious claim
Whether families have a clear path to seek compensation
Whether the provider has met licensing, lease, or contract requirements
A daycare without coverage may still be loving and well-run. But if something serious happens, good intentions do not pay medical bills or legal costs.

How parents can verify daycare insurance
A reputable daycare should not be offended by insurance questions. In fact, many directors expect them. Asking calmly and directly can make the conversation simple.
Ask for a certificate of insurance
The most common proof is a certificate of insurance, often called a COI. This document summarizes the daycare’s policy details, such as the insurer, policy dates, type of coverage, and coverage limits.
When reviewing it, look for:
The daycare’s legal business name
Current policy dates
The insurance company name
General liability coverage
Any listed exclusions that seem relevant
Coverage connected to transportation, if the daycare drives children
A certificate is not the full policy, but it is a useful start. If anything looks confusing, ask the daycare to explain it or request clarification from the insurance agent.
Confirm that the policy is active
A certificate can be outdated. Ask whether the policy is currently active and when it renews. Some parents also ask the daycare to have its insurance agent send proof directly.
That may feel formal, but it is common in many industries. If a provider hesitates, it does not always mean there is a problem. Smaller providers may not know the process. A responsible provider should still be willing to help confirm coverage.
Check state licensing requirements
Childcare licensing is handled at the state level in the United States. Requirements vary widely. Some states require proof of liability insurance for certain daycare settings. Others may require providers to tell parents if they do not carry coverage.
Parents can usually search for a daycare through a state childcare licensing website. These records may show license status, inspection history, complaints, and enforcement actions. They may not show full insurance details, but they can help confirm whether the provider is in good standing.
Read the parent handbook
Many daycares include insurance information in the parent handbook or enrollment packet. Look for sections about:
Injury procedures
Emergency care
Medication and allergy policies
Field trips
Transportation
Incident reports
Parent notification
Liability waivers
A waiver does not replace insurance. It also may not prevent all claims. If a daycare relies heavily on broad waivers but will not discuss insurance, ask more questions before enrolling.
Ask practical follow-up questions
Parents do not need to sound confrontational. A few plain questions can tell you a lot.
Try asking:
“Do you carry liability insurance for the daycare?”
“Can I see a current certificate of insurance?”
“Does your policy cover accidents on the playground?”
“Are field trips and transportation covered?”
“Do you have coverage for food allergy incidents?”
“How do you handle injury reports and parent notifications?”
“Who should parents contact if there is a serious incident?”
Listen not only to the answer, but also to the tone. A prepared provider will usually answer clearly or offer to find the information. A vague answer, annoyance, or refusal may be a sign to slow down.
What can happen if a daycare has no insurance
The biggest risk of an uninsured daycare is not that accidents become more likely. Insurance does not supervise children. The risk is that when an accident does happen, there may be no reliable financial support behind the provider.
That can create painful problems for families and the daycare.
Medical costs may become harder to resolve
Imagine a child falls from a climbing structure and breaks an arm. The center calls the parent, documents the injury, and cooperates. If the daycare has liability coverage and the claim is covered, the insurer may help evaluate responsibility and pay eligible costs.
Without insurance, the daycare may need to pay out of pocket. A small home provider might not have the money. Parents may need to use their own health insurance first, argue over bills, or pursue legal action.
That process can be stressful at a time when the child needs calm support.
Legal disputes can become personal
When insurance is involved, claims often go through an insurer and claims adjuster. Without insurance, the dispute may be directly between the parent and provider.
That can strain relationships quickly. A parent may feel ignored. A provider may feel attacked. What began as a childcare relationship can turn into a personal conflict over medical bills, lost wages, and responsibility.
Insurance does not remove emotion from a serious incident, but it can create a clearer process.
The daycare may close after one major claim
A serious injury claim can be expensive. Even if the daycare did nothing wrong, legal defense costs can add up. An uninsured provider may not be able to absorb those costs.
If a center closes suddenly, families may lose care with little notice. Staff may lose jobs. Children may lose a familiar routine.
Coverage helps protect not just one injured family, but also the stability of the program.
Lack of insurance may point to other gaps
No insurance does not automatically mean a daycare is unsafe. Still, it can suggest that the provider has not fully planned for risk.
Parents may want to take a closer look at other areas, such as:
Staff training
Emergency procedures
Background checks
Playground maintenance
Child-to-staff ratios
Medication handling
Allergy communication
Transportation safety
A daycare willing to discuss insurance is often more willing to discuss safety practices in general.

Everyday scenarios that show why coverage matters
Insurance can feel abstract until you picture how a claim might happen. These examples are not legal advice. They are common scenarios that show why coverage matters.
A playground fall during outdoor time
A preschool class goes outside after lunch. One child climbs a short ladder, slips, and lands awkwardly. Staff members respond right away, call the parent, and complete an incident report.
If the equipment was poorly maintained or supervision was lacking, the family may have a claim. Liability insurance can help determine what happened and whether covered costs should be paid.
If the daycare is uninsured, the same facts may lead to a drawn-out dispute.
A food allergy mistake at snack time
A child has a documented dairy allergy. A substitute staff member gives the wrong snack, and the child has a reaction that requires urgent care.
A well-run daycare should have allergy procedures, labeled food, staff training, and emergency plans. If a mistake still occurs, insurance may help with covered medical costs and legal claims.
Parents should ask how the center tracks allergies and whether food-related incidents are part of its coverage.
A field trip transportation incident
A daycare takes children to a local library. During the ride, another driver hits the daycare van. Several children need medical evaluation.
This situation may involve multiple insurance policies, including the other driver’s auto insurance and the daycare’s commercial auto policy. If the daycare transports children but does not carry proper auto coverage, families may face a much more complicated claims process.
Before signing a field trip form, ask how transportation is insured.
A visitor injury at pickup
A grandparent arrives for pickup on a rainy afternoon and slips near the entrance. The injury does not involve a child, but it still happened on daycare property.
General liability coverage may apply to visitor injuries. Without it, the daycare may need to handle the claim alone.
This is one reason liability insurance matters for the whole childcare environment, not only child injuries.
Insurance is one part of a larger safety picture
Proof of insurance should not be the only factor in choosing a daycare. A center can have a policy and still fall short in daily care. A strong choice combines coverage with visible safety habits.
During a tour, pay attention to the basics:
Are staff members engaged with children?
Are exits clear and marked?
Are cleaning supplies locked away?
Does the playground look maintained?
Are babies placed to sleep safely?
Are sign-in and pickup procedures consistent?
Are allergies and medications handled carefully?
Do staff members communicate clearly and respectfully?
Ask about staff training, background checks, emergency drills, illness policies, and incident reports. A good daycare will usually have clear procedures and be willing to explain them.
Insurance is a backstop. Prevention is still the first line of protection.
How to ask without making the conversation awkward
Some parents worry that asking about insurance sounds distrustful. It does not have to. The tone makes a difference.
A simple approach works best:
“I’m reviewing safety information before enrolling. Can you share your current proof of liability insurance and explain what it covers?”
That question is polite, direct, and reasonable. It also shows that you are not looking for problems. You are trying to make an informed decision.
If the provider says yes, review the document and ask follow-up questions if needed. If the provider says no, ask why. There may be a harmless explanation, such as a certificate that needs to be requested from an agent.
If the provider refuses, dismisses the question, or says insurance is unnecessary, treat that as a serious concern.
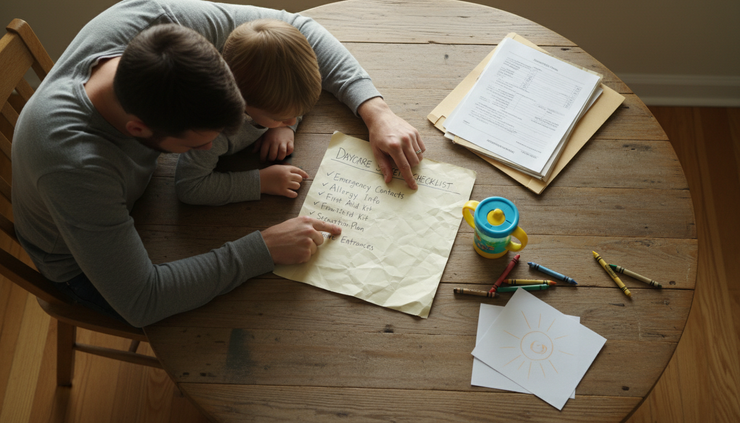
A short checklist before you enroll
Before signing an enrollment agreement, take a few minutes to confirm the basics.
Use this checklist as a guide:
Ask whether the daycare has current liability insurance.
Request a certificate of insurance.
Confirm the policy dates have not expired.
Ask whether playground activities are covered.
Ask about transportation coverage if children ride in daycare vehicles.
Ask how food allergies and medication incidents are handled.
Review the parent handbook for injury and emergency procedures.
Check the daycare’s state licensing record.
Keep copies of important documents.
Trust your instincts if answers feel unclear or rushed.
The goal is not to create fear. The goal is to choose care with clear eyes.
What a reassuring answer sounds like
A daycare that handles this well might say something like:
“We do carry liability insurance. Here is our current certificate. Our policy renews each year, and our agent can confirm coverage if you need that. We also document all incidents and contact parents right away for injuries, allergy concerns, or emergencies.”
That kind of answer tells parents several things. The provider understands the question. The paperwork is available. The daycare has procedures. The staff expects accountability.
A less reassuring answer might sound like:
“We’ve never had a problem, so we don’t need that.”
Past luck is not a safety plan. Even excellent providers can face accidents. Responsible childcare means preparing for what no one wants to happen.
The takeaway for parents
Liability insurance is not the warmest part of choosing childcare. It will never matter as much to a child as a patient teacher, a safe nap space, or a comforting routine. But for parents, it is a practical sign that the daycare is prepared to take responsibility if something goes wrong.
Ask the question. Request proof. Review the handbook. Check licensing records. Then look at the full picture, including staff, safety habits, communication, and how the daycare responds to your concerns.
A confident daycare choice does not come from avoiding hard questions. It comes from getting clear answers and knowing the people caring for your child have planned for both ordinary days and unexpected ones.


Comments